
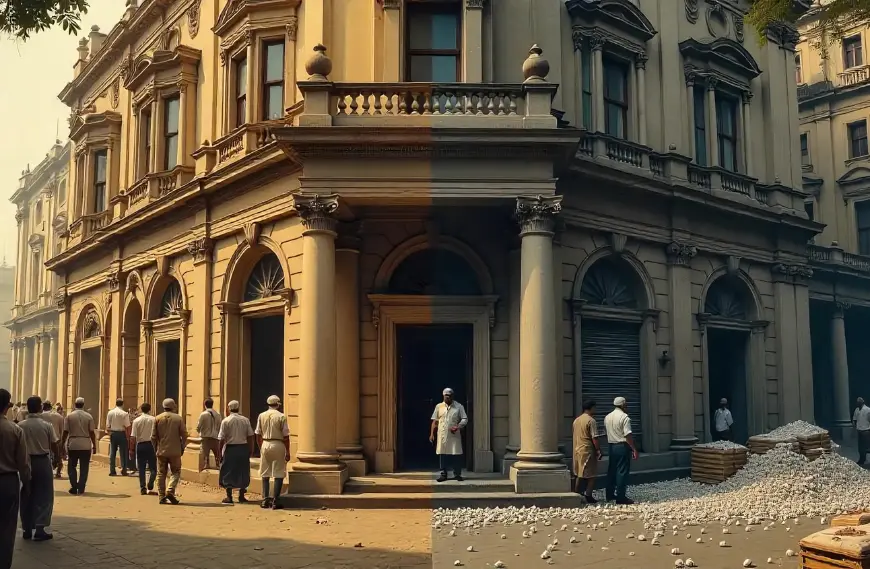
In 1867, Bombay, the bustling heart of colonial India’s commerce, was rocked by a financial catastrophe that would echo through history. The Presidency Bank of Bombay, a pillar of the city’s economy, collapsed under the weight of a speculative cotton boom gone bust, wiping out the savings of thousands and exposing the fragility of India’s early banking system. Triggered by the end of the American Civil War, fueled by greed and mismanagement, and ignored by colonial authorities, this was India’s first major bank crisis, a tale of ambition, betrayal, and resilience that left scars on a city and its people. Drawing on historical records and personal stories, this article unravels the rise and fall of the Presidency Bank of Bombay, its devastating impact, and the lessons it holds for modern India.
The rise of a financial titan
Founded in 1840 under the East India Company’s charter, the Presidency Bank of Bombay was one of three presidency banks, alongside Bengal (1806) and Madras (1843), that powered colonial India’s economy. A hybrid of commercial and government banking, it issued currency, managed public debt, and financed trade, with a paid-up capital of ₹2 crore (roughly ₹500 crore in 2025). By the 1860s, it was a cornerstone of Bombay’s thriving port, underwriting cotton and opium exports to Britain and China. “The Bank of Bombay was the lifeblood of commerce,” wrote James Maclean in his 1876 Guide to Bombay.
Bombay, with its 800,000 residents, was India’s commercial hub, its docks teeming with merchants like Jamsetjee Jejeebhoy, a Parsi trader on the bank’s board. The bank’s branches across western India served everyone from wealthy banias to small shopkeepers, offering 10% interest on fixed deposits, a rarity that inspired trust. “It was seen as unshakeable,” notes historian Dwijendra Tripathi. Yet, this trust masked a brewing storm, ignited by a global event: the American Civil War.
The cotton boom: A speculative fever
The American Civil War (1861–1865) disrupted cotton supplies from the U.S. South, turning Bombay’s cotton into a global lifeline for Britain’s textile mills. Prices skyrocketed, a bale worth ₹150 in 1860 fetched ₹1,000 by 1864, per The Bombay Gazette. Merchants, traders, and speculators rushed to profit, transforming Bombay into a city of frenetic wealth. “Cotton was king,” recalled merchant Dwarkanath Mulji in 1866. “Every man with a bale was a prince.”
The Presidency Bank of Bombay fueled this frenzy, extending loans to cotton traders and speculative ventures, often without collateral. By 1864, its loan portfolio reached ₹10 crore, with 60% tied to cotton, according to the 1868 Bombay Bank Commission. Directors, many with stakes in cotton firms, approved risky advances, including ₹2 crore to speculator Premchand Roychand, dubbed the “Cotton King.” Over 80 joint-stock companies, like the Back Bay Reclamation Company, sprang up, with shares soaring from ₹5,000 to ₹50,000 in months. Depositors, lured by high returns, poured savings into the bank, unaware of its dwindling reserves.
The crash: A financial ruin
The bubble burst in April 1865, when the Civil War ended, and American cotton flooded global markets. Prices plummeted—a bale fell to ₹200 by December. Bombay’s cotton-dependent economy unraveled: merchants defaulted, joint-stock companies collapsed, and shares like Back Bay’s crashed to ₹500. “The city was a graveyard of dreams,” wrote The Times of India in January 1866. The Overend Gurney bank’s failure in London in 1866 tightened global credit, worsening the panic.
The Presidency Bank, overexposed to cotton, faced a liquidity crisis. Bad loans exceeded ₹6 crore, and depositors began withdrawing funds. Raising interest rates to 12% failed to stem the tide. “The bank was a sinking ship,” noted editor Robert Knight in 1867. On March 15, 1867, the bank suspended operations, collapsing with liabilities of ₹12 crore against assets of ₹4 crore. Depositors, like cloth merchant Gopal Rao, who lost ₹10,000, were left with nothing. “My savings were my life’s work,” Rao wrote in a petition preserved in the Maharashtra State Archives.
The human toll: A city in despair
The collapse devastated Bombay’s residents. Thousands, from wealthy Parsis to modest traders, lost their savings. The Bombay Gazette reported suicides among ruined merchants, and small businesses reliant on bank credit shuttered. Cotton exports dropped 40% in 1867, per colonial records, crippling trade. In rural Maharashtra, cotton farmers faced unpaid debts, some falling into bonded labour. “The bank’s failure broke our markets,” wrote a Poona trader in The Hindu.
The crisis hit hardest because of the colonial system’s lack of safeguards. With no deposit insurance, central bank, or bailout, depositors had no recourse. Protests erupted, demanding compensation, but the East India Company, weakened post-1857 Sepoy Mutiny, offered none. “The government stood by as our money vanished,” Rao lamented. The crisis deepened distrust in British banks, a sentiment that lingered for decades.
Mismanagement and colonial neglect
The Bombay Bank Commission (1868) exposed the bank’s reckless practices: unsecured loans to cronies, shoddy accounting, and no reserve fund. “The directors acted as if the boom would never end,” the report concluded. Colonial authorities, focused on taxes over stability, failed to enforce oversight. “The East India Company was no guardian,” says historian Amalendu Guha. Unlike today’s ₹5 lakh deposit insurance, 1867 offered no protection, leaving depositors vulnerable.
The bank’s board, dominated by British officials and elite traders, prioritized profits over prudence. Loans to speculators like Roychand, who lost millions in failed ventures, drained reserves. The absence of modern regulations, like those later introduced in the Banking Regulation Act of 1949, allowed such excesses to flourish.
Aftermath: Reforms and Recovery
The colonial government liquidated the bank in 1868, merging its assets into the New Bank of Bombay, which joined the Imperial Bank of India in 1921 (later the State Bank of India in 1955). Depositors received about 30 paise per rupee over years, but most never recovered fully. “The loss lingered for a generation,” says Tripathi.
The crisis spurred modest reforms. The Indian Companies Act (1866) was amended in 1882 to regulate joint-stock firms, and bank charters required higher reserves. The Paper Currency Act (1861) had already centralized note issuance, reducing risks. However, comprehensive oversight awaited post-Independence laws. The crisis also shifted Bombay’s financial landscape, with Indian merchants turning to indigenous bankers like Marwaris and Chettiars for safer lending. “The collapse taught us to trust our own systems,” notes Guha.
Lessons for today
The 1867 crisis resonates in modern India, where speculative bubbles and banking failures persist. The Global Trust Bank’s 2004 collapse and IndusInd Bank’s 2025 accounting issues echo the Presidency Bank’s overexposure. Today’s ₹5 lakh deposit insurance, while an improvement, falls short for small businesses, as depositor Anil Sharma told The Hindu in 2025: “I read about 1867, it feels like we’re still fighting those battles.” Economist Ila Patnaik emphasizes stronger RBI oversight to prevent such crises.
The human cost remains universal. Just as Gopal Rao lost his livelihood, modern depositors fear for their savings. The crisis underscores the need for diversification, transparency, and public trust in banking, principles John Maynard Keynes later championed, noting India’s banking required “the safest possible principles.”
A cautionary legacy
India’s first bank crisis was a tragedy of hubris, speculation, and neglect. The Presidency Bank of Bombay, once a symbol of colonial might, became a cautionary tale, its collapse a scar on the city it helped build. For Bombay’s residents, it was a betrayal of trust, a reminder that banks, without vigilance, can falter. As India modernizes its financial systems, the lesson of 1867 endures: protect the people’s money, or risk breaking their dreams.
Key events in the 1867 presidency Bank of Bombay crisis
| Year | Event |
| 1840 | Presidency Bank of Bombay established under East India Company charter. |
| 1861 | American Civil War begins, triggering a cotton boom in Bombay. |
| 1864 | Cotton prices peak at ₹1,000 per bale; bank loans reach ₹10 crore. |
| 1865 | Civil War ends; cotton prices crash to ₹200 per bale, sparking defaults. |
| 1866 | Overend Gurney crisis in London tightens global credit, worsening panic. |
| 1867 | Presidency Bank of Bombay collapses with ₹12 crore liabilities. |
| 1868 | Bank liquidated; New Bank of Bombay formed with partial repayments. |
| 1921 | Presidency Banks merge into Imperial Bank of India. |
| 1955 | Imperial Bank becomes State Bank of India via nationalization. |
